TradingKey - On Thursday (October 8) Eastern Time, surging oil prices and rising US Treasury yields jointly weighed on risk appetite, causing futures on the three major US stock indexes to fall across the board pre-market, though analyst ratings, energy prices, and corporate earnings continued to drive clear divergence among individual stocks.
As of press time, Dow futures fell 0.87%, S&P 500 futures fell 0.49%, and Nasdaq 100 futures fell 0.73%.
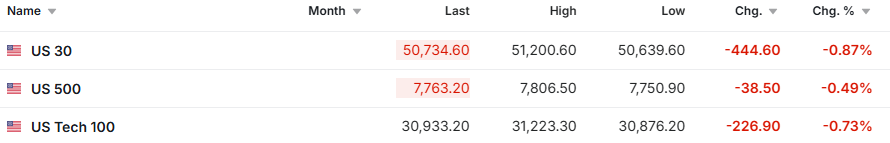
Source: Investing
In commodities, international oil prices surged sharply. WTI (USOIL) crude oil rose about 4.3% to around $92.7; Brent (UKOIL) crude oil rose about 4.2%, breaking above $105. With the US and Iran yet to reach an agreement to end the conflict, combined with potential US reassessment of military options against Iran, the market rapidly priced in a crude supply disruption risk premium. Gold (XAUUSD) fluctuated near $4,120, as geopolitical safe-haven demand was offset by a stronger US dollar and rising Treasury yields.
In cryptocurrencies, Bitcoin (BTC) fell about 1%, trading near $82,500. Rising oil prices and expectations of further Fed rate hikes weakened demand for highly volatile risk assets.
Market Moves
Palantir (PLTR) rose about 2.4% in pre-market trading. Goldman Sachs (GS) upgraded Palantir from Neutral to Buy with a price target of $230; Yorkville Ives also assigned an Outperform rating and a $250 price target, believing sovereign AI and enterprise AI demand will continue to expand the company's addressable market.
ExxonMobil (XOM) rose about 2.1% in pre-market trading. A rapid rise in international oil prices boosted earnings expectations for upstream energy companies; Chevron (CVX) also rose about 2.2% in pre-market trading.
PepsiCo (PEP) rose about 2% in pre-market trading. The company's third-quarter revenue grew 5.6% year-over-year to $25.27 billion, beating market expectations of $24.95 billion; adjusted earnings per share came in at $2.34, also better than expected. However, the company lowered its full-year adjusted EPS growth guidance from 5%-7% to 2.5%-3.5%.
Intel (INTC) fell about 2.5% in pre-market trading. The market continues to focus on Intel's specific role in Elon Musk's Terafab AI chip factory plan, while chip stocks generally faced profit-taking pressure following rising U.S. Treasury yields and recent sharp gains.
TSMC (TSM) ADR fell about 1.6% in pre-market trading. TSMC reported September revenue of NT$511.86 billion, up 54.6% year-over-year; cumulative revenue in the first nine months of this year grew 41.1%. Although AI chip demand remains strong, pressure from high interest rates and a broader pullback in the semiconductor sector weighed on the stock price.
Market News
The US and Iran have not reached an agreement to end the conflict. According to The Associated Press citing The Atlantic, the White House has asked the Pentagon to study options for striking Iran ahead of the November midterm elections. The report cited two anonymous officials, and the action plans have not been officially confirmed.
Federal Reserve officials continued to signal rate hikes. Minutes of the September meeting showed that a majority of officials believed another rate hike before the end of the year could be appropriate; Fed Governor Waller said Thursday he expects further rate hikes will be needed if economic data continues to meet expectations, but hikes do not need to be consecutive.
Broadcom is reportedly planning over $50 billion in AI chip financing. According to The Wall Street Journal citing people familiar with the matter, Broadcom (AVGO) is arranging over $50 billion in financing for an OpenAI custom AI chip project; Oracle (ORCL) and SpaceX (SPCX) are also studying large-scale chip procurement financing. The negotiations remain at an early stage, and the amounts may change.
The White House will hold an AI science summit. According to a White House preview cited by Axios, Trump will attend the summit centered on the "Genesis Mission," and companies such as AMD (AMD), OpenAI, and Anthropic will announce over $1 billion in industry commitments, while the U.S. National Science Foundation and the Department of Energy will also contribute over $100 million to support AI scientific tools.
Micron (MU) union in Taoyuan, Taiwan obtains strike authorization. The union at Micron Technology's Taoyuan plant stated that approximately 99% of the 1,994 voting members supported a strike, with the dispute mainly centering on the bonus system and establishing a long-term profit-sharing mechanism. The union has not yet set a strike date, and the relevant plants are currently operating normally; Taiwan is a major production base for Micron's DRAM and HBM chips, and the Taichung union is still in negotiations.
Key Data and Events Preview
At 8:30 AM ET on October 8, the US will release initial jobless claims data.
At 10:00 AM ET on October 8, the US will release August wholesale inventories and wholesale sales data.
At 10:30 AM ET on October 8, the US will release EIA natural gas storage data.
At 10:40 AM ET on October 8, Minneapolis Fed President Kashkari will participate in a research conference conversation.
At 1:00 PM ET on October 8, the US Treasury will release the 30-year Treasury bond auction results.
Find out more