TradingKey - Amazon is trading at $251.19 as of the latest close on September 17, a gain of 2.13% and very close to our chart reference of $251.20. From a technical perspective, the stock is trading above the trendline support of $244.58 but remains below the resistance at $255.71 to $257.67, and thus the uptrend is not yet confirmed. From a fundamental perspective, the recent positive developments regarding the growth of the company’s cloud business, as well as improvements in the company’s advertising business and retail business, warrant the positive move in the stock. The biggest risk to the company is likely its high capital expenditures. Management has recently disclosed that the company expects approximately $220 billion of cash capital expenditures in 2026, while the company’s free cash flow has recently been negative.
AWS Growth Is the Core Bullish Driver
The company recently reported Q2 revenue of $200.6 billion. Operating income for the quarter came in at $27.5 billion, an increase of 43% from the year prior. The company’s cloud computing business, AWS, accounted for roughly 78% of the year over year increase in operating income. While there is some uncertainty regarding the company’s other business segments, it is widely known that the demand for cloud computing services is growing, and similar to many of its peers, the company has constraints in supplying its services.
According to management, the lion’s share of the AWS capacity being added in 2027 is largely reserved, and quite a bit of capacity is already reserved for 2028. Therefore, management has stated that there is more demand for AWS than capacity in the short-term. Based on the above, I would agree with most market participants that the near-term demand for cloud computing is growing and there is an opportunity for further pricing power.
AI and Custom Chips Are Becoming Material Businesses
Amazon has disclosed that its AI business and chips business have each surpassed $25 billion in annualized revenue run rates. Trainium provides an alternative to Nvidia GPUs for some AI workloads, while Graviton provides AWS-designed CPUs for general-purpose and AI-supporting compute. Additionally, Amazon Bedrock keeps AWS’s platform model neutral. As of now, bedrock has approximately 225,000 active customers, with 80% of the Fortune 100 as users. From an investment perspective, this model adds significant value.
As of now, the model does not indicate a preference to whether a customer uses Amazon, OpenAI, or Anthropic’s large language models, thus Amazon is able to monetize AI infrastructure regardless. While the monetization of Anthropic models is positive for Amazon, in the long-run, this model should not affect Amazon’s operating results in a material way. Investors should consider the operating results of Amazon separate from the accounting results of Amazon. In Amazon’s recent earnings release, reported net income was materially boosted by a $53.4 billion non-operating pre-tax gain, primarily from Amazon’s investment in Anthropic. Thus, for equity valuation purposes, operating results should be the focus.
CapEx Is the Main Financial Risk
As of 2026, Amazon expects roughly $220 billion in capital expenditures (CapEx). The capital outlay will largely be for artificial intelligence (AI) data centers, chips, and networking equipment and memory. This reinforces Amazon’s position as a hyperscaler. Amazon does not provide full-year 2026 revenue guidance. Historical operating cash flow will help support the investments. During the last 12 months, cash flow from operations was $161.4 billion, an increase of 33% from the previous year. Capital expenditures during the last 12 months were approximately $169 billion, leaving free cash flow at -$7.6 billion. This will be one of the primary focal points when Amazon reports financial results for Q3 2026. Positive demand for AWS has been reported. The question will be, will the investments for the build-out of the infrastructure result in improved free cash flow and return on capital invested for Amazon?
Generac Deal Highlights the Physical AI Bottleneck
The long-term supply agreement with Generac illustrates the level of competitive AI and edge computing resources required. While many companies have announced AI strategies, the means to implement and bring the strategies to market may not be available. Amazon does.
Amazon recently entered a multi-year agreement with Generac to build out Amazon’s AI infrastructure. Under this agreement, Generac expects to receive approximately $2.4 billion from Amazon in 2027 and 2028 for the purchase of backup power generators. As part of the agreement, Generac also issued Amazon a warrant to acquire up to 1.69 million shares, with most of the warrant vesting based on Amazon generator purchases that could total up to $8 billion. As such, I view the Generac agreement as a positive development. The Generac deal demonstrates that Amazon is preparing the physical infrastructure required to support the AI work already committed by customers.
AI Safety Is a Fresh Weekend Theme
This week Amazon also released its position on the use of advanced AI systems, stating that AI models should be released only when they are ready and safe to use, following rigorous testing and strong safeguards. Amazon stopped short of calling for an industry-wide slowdown in AI development. Thus, Amazon’s comments do not currently signal a slowdown in AI and infrastructure investments; such a slowdown would be more consequential for Amazon.
Retail and Advertising Remain Strong
Other lines of business outside of AWS are showing improvement. North American sales by $116.2 billion and International sales by $42.2 billion. North American and International operations generated operating income of $9.1 billion and $1.7 billion respectively. Advertising is showing improvement and rose by 26% to $19.8 billion. It is helpful to consider advertising revenues because it shows the company can derive operating income from various sources and not rely primarily on AWS.
What Matters When Markets Reopen
In the near-term, there are a few areas to focus on. First, can Amazon continue to hold the $244.58 level? Second, will the AI sector and Treasury yields continue to trade in conjunction? Finally, are there signs that AI infrastructure spending is slowing? With the majority of AWS's 2027 capacity reserved, this would be the biggest risk to Amazon.
Amazon Technical Analysis: $257.67 Is the Recovery Trigger
After recently bouncing from the support zone of $244.58, Amazon’s stock price closed at $251.19. I’m interested in the stock from this level because the rising trend line and horizontal support meet at $244.58. Furthermore, the stock is currently trading below the moving average at $255.71 and the previous support at $257.67. Because of this, the higher time frame trends and higher time frame moving averages remain unfavorable for a potential long position.
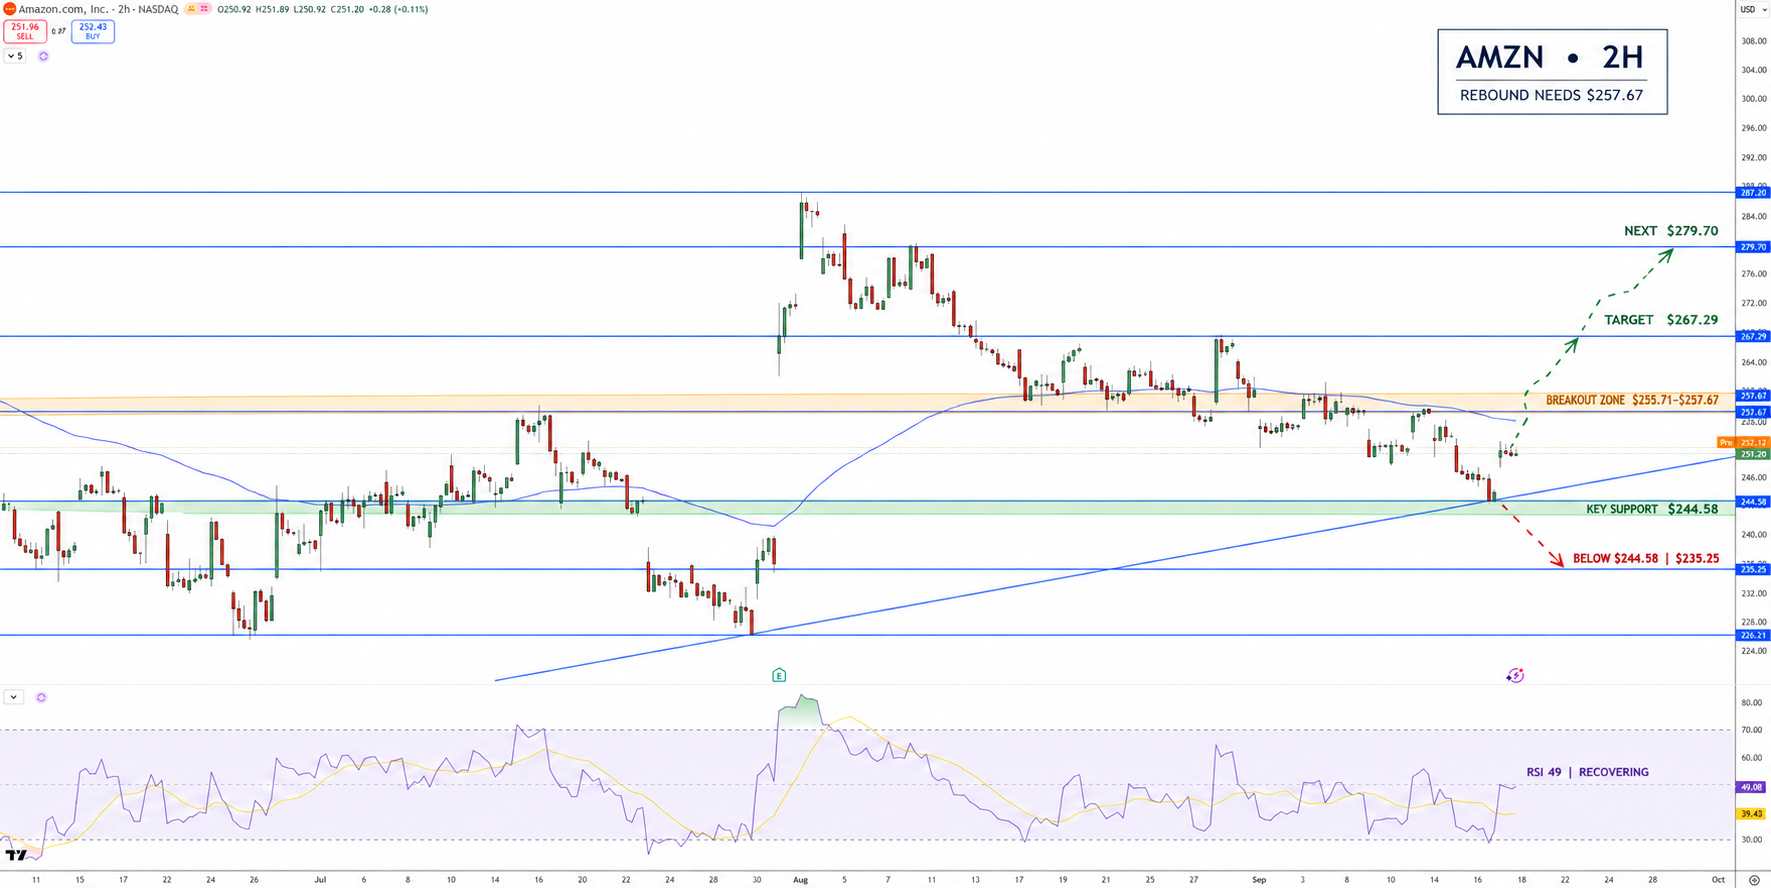
Amazon Stock Price Chart - Source: Tradingview
The Relative Strength Index (RSI) is at 49. Because the RSI is trending upward and is currently above the signal line at 39, I can say the present trend is neutral. Keep in mind that the current RSI reading is still below the 50 neutral level.
Taking a bullish perspective, the move above the resistance area at $255.71 and $257.67 would increase the likelihood of a further move to the upside and above the next major resistance at $267.29.
If the support at $244.58 is lost, the stock could move to the downside and challenge the next major support at $235.25 and $226.21.
Based upon all of the aforementioned information, I believe that the more attractive setup to buy Amazon stock is after a confirmed move above $255.71 to $257.67.
Why is Amazon stock in focus this weekend?
Amazon’s cloud computing division grew 37% year over year in Q2 2026 and the backlog is at $496 Billion. Furthermore, Amazon is securing physical AI infrastructure through recent agreements. Negative free cash flow and planned 2026 $220 billion CapEx create contention around capital allocation.
What level confirms a stronger AMZN rebound next week?
If the stock manages to end 2 hours in a session above $257.67, then we may expect it to advance to the level of $267.29 and $279.70 in the subsequent sessions. A move below $244.58 should be considered bearish and may lead to a test of the next support level at $235.25.
Bottom Line
Amazon's structure looks poised to make a move higher, and the weekly time frame gives us a good risk/reward. The company has a sizable backlog and positive forward lookings. With recent demand trends and inventory levels as our guide, further expansion in Amazon's AI division looks likely. The company has contracts in place with suppliers to build out the physical infrastructure to support the AI. The company has significant CapEx, and whether the business can sustain and monetize that CapEx remains to be seen. I expect Amazon will trade between 244.58 and 257.67 next week, but a clear break above 257.67 would target 267.29, and potentially 279.70.
Find out more