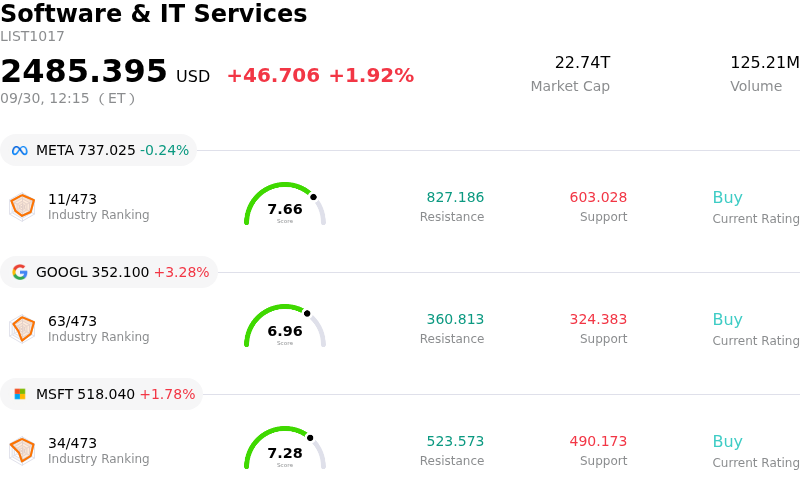
Accenture PLC (ACN) moved up by 3.18%. The Software & IT Services sector is up by 1.92%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) down 0.24%; Alphabet Inc Class A (GOOGL) up 3.27%; Microsoft Corp (MSFT) up 1.79%.
What is driving Accenture PLC (ACN)’s stock price up today?
Accenture experienced positive momentum as market participants actively positioned ahead of the company's fiscal fourth-quarter earnings release, scheduled before the opening bell on October 1. Investors displayed renewed confidence in the IT services leader following a period of sector-wide pressure and analyst rating adjustments earlier in the month. The broader market environment reflected a shift back toward high-quality technology enablers, with buyers driving up shares in anticipation of disciplined cost management and steady operational execution.
Underpinning this positive sentiment is Accenture's expanding footprint in enterprise artificial intelligence and cloud modernization. Recent announcements highlight the company's accelerating pivot toward large-scale generative AI implementations, moving beyond initial pilot projects into full-scale organizational transformations. Strategic joint initiatives with leading AI developers, alongside specialized solution launches and enterprise software integration wins, have reinforced the company's positioning as a key partner for digital transformation. High-profile project completions across global supply chains and cloud platforms demonstrate that client demand for operational efficiency remains resilient.
From a financial perspective, investors are focusing on the firm's robust cash flow generation and capital allocation strategy. Management's ongoing commitment to returning capital to shareholders through share buybacks and consistent dividend growth continues to offer downside protection for valuation. While enterprise IT spending has faced selective customer discretionary pullbacks in recent quarters, steady demand in managed services and government technology engagements is helping offset soft spots in traditional consulting. Heading into the official financial report, market attention will center on quarterly bookings growth, the monetization rate of AI contracts, and executive commentary regarding forward revenue targets.
Technical Analysis of Accenture PLC (ACN)
Technically, Accenture PLC (ACN) shows a MACD (12,26,9) value of -3.120, indicating a neutral signal. The RSI at 51.549 suggests neutral condition and the Williams %R at 59.169 suggests sell condition. Please monitor closely.
Media Coverage of Accenture PLC (ACN)
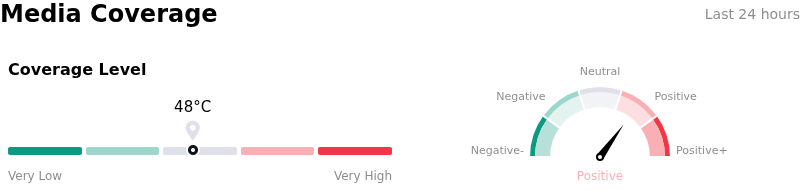
In terms of media coverage, Accenture PLC (ACN) shows a coverage score of 48, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Accenture PLC (ACN)
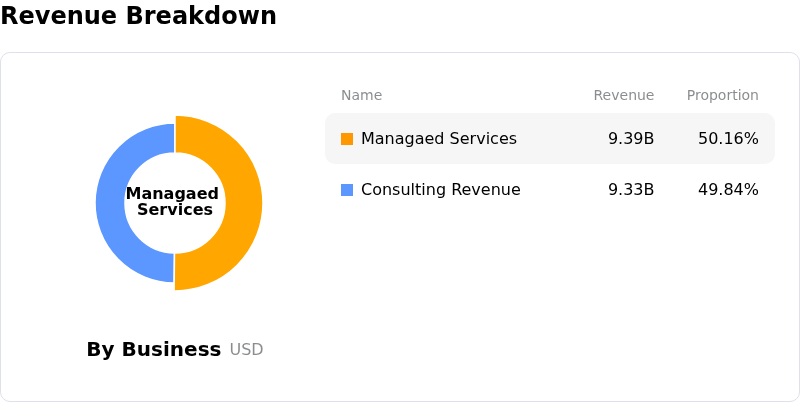
Accenture PLC (ACN) is in the Software & IT Services industry. Its latest annual revenue is $69.67B, ranking 6 in the industry. The net profit is $7.68B, ranking 14 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $200.46, a high of $329.00, and a low of $150.00.
More details about Accenture PLC (ACN)
Company Specific Risks:
- Surging Pre-Earnings Volatility and Bearish Derivatives Positioning: Ahead of its fiscal Q4 financial results, option implied volatility surged above 100%, with straddle pricing indicating an expected stock price swing of 7.5%. Put option volume heavily outweighs calls as institutional investors position for sequential declines in both quarter-over-quarter earnings per share ($3.19 consensus vs. $3.80 in Q3) and net revenue ($18.05 billion expected vs. $18.72 billion in Q3).
- Institutional Analyst Downgrades on Sluggish Organic Growth: Prominent Wall Street research firms, including Guggenheim and Wells Fargo, recently downgraded Accenture to Neutral and Equal Weight ratings, citing a lack of near-term fundamental catalysts. Analysts warn that fiscal 2027 organic constant-currency revenue growth may stagnate at just 1% to 2%, leaving the company heavily reliant on aggressive M&A capital deployment to mask underlying top-line deceleration.
- Structural AI Disruption and Labor-Model Cannibalization: Rapid enterprise adoption of automated and agentic AI models poses a direct threat to Accenture's legacy billable-hours IT advisory model. Analysts stress that automated workflows risk commoditizing enterprise consulting and compressing billable project hours faster than new, high-margin AI partnership contracts can convert into recognized revenue.
- Declining Contract Bookings and Enterprise IT Budget Friction: Quarterly new bookings slipped year-over-year to $19.3 billion from $19.7 billion, indicating prolonged sales cycles and reduced client commitment to discretionary IT consulting projects. This contraction is compounded by federal spending softness and ongoing international geopolitical headwinds that continue to delay large-scale enterprise integration rollouts.
Find out more