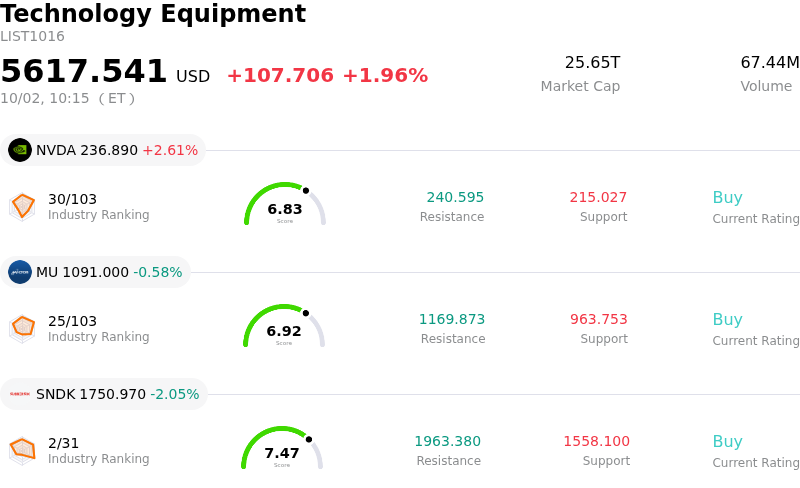
Arm Holdings PLC (ARM) moved up by 6.94%. The Technology Equipment sector is up by 1.96%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 2.59%; Micron Technology Inc (MU) down 0.63%; SanDisk Corporation (SNDK) down 2.26%.
What is driving Arm Holdings PLC (ARM)’s stock price up today?
Arm Holdings experienced strong upward momentum accompanied by heightened intraday volatility as institutional investors aggressively stepped back into high-conviction artificial intelligence infrastructure enablers following recent sector pullbacks. Market sentiment was buoyed by momentum surrounding Arm's expanding integration across next-generation compute workloads, particularly its foundational role in data center CPUs and agentic AI execution frameworks. Investor enthusiasm has been further reinforced by growing adoption of Arm's architectural IP within major hyperscaler environments and next-generation safety platforms, including Nvidia's Open Agent Safety Platform and Sentry architecture, where Arm-based cores manage both AI agent execution and real-time monitoring.
The underlying fundamental thesis for Arm continues to strengthen as the global semiconductor landscape shifts toward custom silicon and power-efficient compute architectures. Management's updated disclosures regarding strong demand visibility for its first in-house data center processor, combined with expanding enterprise commitments, have significantly reinforced multi-year growth expectations. Furthermore, the accelerating migration of licensee product portfolios from legacy architectures to high-margin Armv9 designs and Compute Subsystems is generating substantial royalty expansion. Because Armv9 commands significantly higher royalty rates than predecessor designs, the ongoing transition across premium smartphones, edge computing devices, and cloud servers provides a structural tailwind to corporate margins.
From an institutional strategy perspective, the recent trading dynamics highlight a clear appetite among asset managers to capitalize on technical pullbacks in premier semiconductor names ahead of upcoming quarterly financial reports. While elevated valuation multiples and semiconductor supply chain bottlenecks require precise execution, the rapid rise in custom cloud chips built on Arm architecture across major technology hyperscalers underscores its structural transition from a mobile-centric IP provider into a dominant data center compute standard. Investors remain closely focused on the pace of custom silicon delivery and royalty revenue conversion as key indicators for sustained momentum.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of 3.186, indicating a buy signal. The RSI at 59.814 suggests neutral condition and the Williams %R at 25.122 suggests buy condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
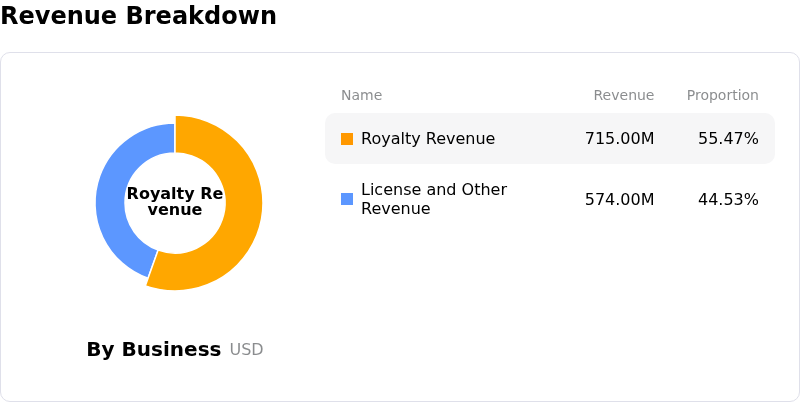
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $284.78, a high of $480.00, and a low of $125.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Valuation Multiples and Volatility Sensitivities: Trading at elevated forward earnings multiples exceeding 100x, the stock remains exceptionally vulnerable to aggressive profit-taking and sharp intraday pullbacks whenever broader semiconductor market sentiment shifts.
- Executive Insider Share Disposal: SEC disclosures highlighting a $3.12 million share sale by CFO Jason Child under a Rule 10b5-1 trading plan have spurred fresh risk-off sentiment and added supply pressure, amplifying concerns surrounding management's near-term outlook.
- Margin Dilution from AGI CPU Hardware Pivot: Management's strategic transition toward selling full AGI CPU silicon and complex Compute Subsystems introduces initial gross margins in the high 30% to low 40% range, diluting Arm's legacy high-margin (~90%+) pure-play IP licensing profile as hardware production scales.
- Litigation Uncertainty and Geopolitical Concentration: Lingering legal disputes with major licensee Qualcomm ahead of a scheduled trial, coupled with tightening export control restrictions on Arm China operations (accounting for roughly 20% of total sales), create persistent overhangs on licensing expansion and international revenue execution.
Find out more