TradingKey - ASML Holding (ASML) has many chips in the air in the run-up to Sunday as AI-fueled semiconductor investing gains traction with TSMC, Samsung, SK Hynix, Intel and more. The latest completed U.S. session available for preparation is October 8, with ASML ending the day at $1,769.79, down 1.95%.
The next significant event on the calendar is the release of Q3 results on Wednesday, October 14. Management previously commented that they expect revenue in the range of €11 billion to €12 billion, and a gross margin in the range of 55-57%, which would both represent substantial improvements from Q2 results, in which the company posted revenue of €9.33 billion.
Hyper NA Extends the Long-Term Technology Lead
Engineers from ASML and Carl Zeiss detailed Hyper NA in a paper reported on October 8. Similar to High-NA EUV, this next-generation lithography platform could print features more than one-third smaller than current High-NA EUV tools and may become operational around 2036, although production is not yet committed.
I believe Hyper NA will not be a significant near-term growth driver. Longer-term, however, it could strengthen ASML's moat. The company is already working on the next generation of High-NA EUV, further extending the lead over its peers.
High-NA Is Moving Into Production
High-NA EUV is much more financially relevant today. Intel already uses the technology in high-volume manufacturing on select Intel 18A layers, and ASML and Intel said more than one million wafers have been processed across testing, R&D and production.
Samsung and SK Hynix are preparing a broader adoption in the second half of the decade, while TSMC is expected to follow. ASML is also working with customers to develop larger photomasks and other changes to the ecosystem to increase High-NA productivity.
AI Demand Has Already Lifted Guidance
Q2 revenue came in at €9.33 billion, net income was €2.92 billion and gross margin was 54.0%. The company sold 86 new lithography systems, a 28% increase from Q1 and IBSM revenue came in at €2.76 billion.
Because of these results, management increased the revenue guidance for 2026 to €43 - €45 billion from €36 - €40 billion and increased expected gross margin to 54 - 56% from 51 - 53%.
These changes reflect the current strength in the semi market. Customers are moving beyond discussions on AI. They are increasing capital expenditures to fund wafer fabs.
Capacity Is Becoming Scarce
According to Reuters, capacity of low-NA EUV systems is expected to grow by about 30% in 2027 from around 65 systems in 2026, while another 30% increase is being explored for 2028. Similar growth is expected with DUV immersion capacity.
Reuters reported that almost all of EUV capacity for 2027 has already been booked, which provides visibility and supports pricing power. Additionally, the growing installed base provides opportunities to generate service and upgrade revenues.
China Remains the Main External Risk
China is ASML’s biggest geopolitical risk. ASML is not permitted to sell EUV systems to China, while export restrictions also impact some advanced DUV systems.
Reuters stated that China is approximately 20% of ASML’s sales. Further restrictions on DUV systems and servicing would also negatively impact ASML, but stronger demand for ASML’s products in other geographies could partially mitigate this.
Wednesday’s Earnings Could Reset Expectations
For the quarter, I would zero in on EUV bookings, High-NA orders, Q4 guidance, comments on 2027 capacity, exposure to China, and gross margin.
Current expectations at $1,769.79 are already elevated. I’d feel better if I saw further forward steps up in demand for 2026 or 2027 and continued gross margin expansion. Conversely, I’d be concerned by weakness in bookings, further customer fab delays, and/or tighter export restrictions on China.
ASML Technical Analysis: ASML Tests $1,756 Support as Bearish Momentum Threatens Recovery
ASML closed at $1,769.79 on October 8, down from a resistance level at $1,870.25. The sharp decline from $1,801.08 has brought the price action back down to test the rising short-term trendline and the support cluster.
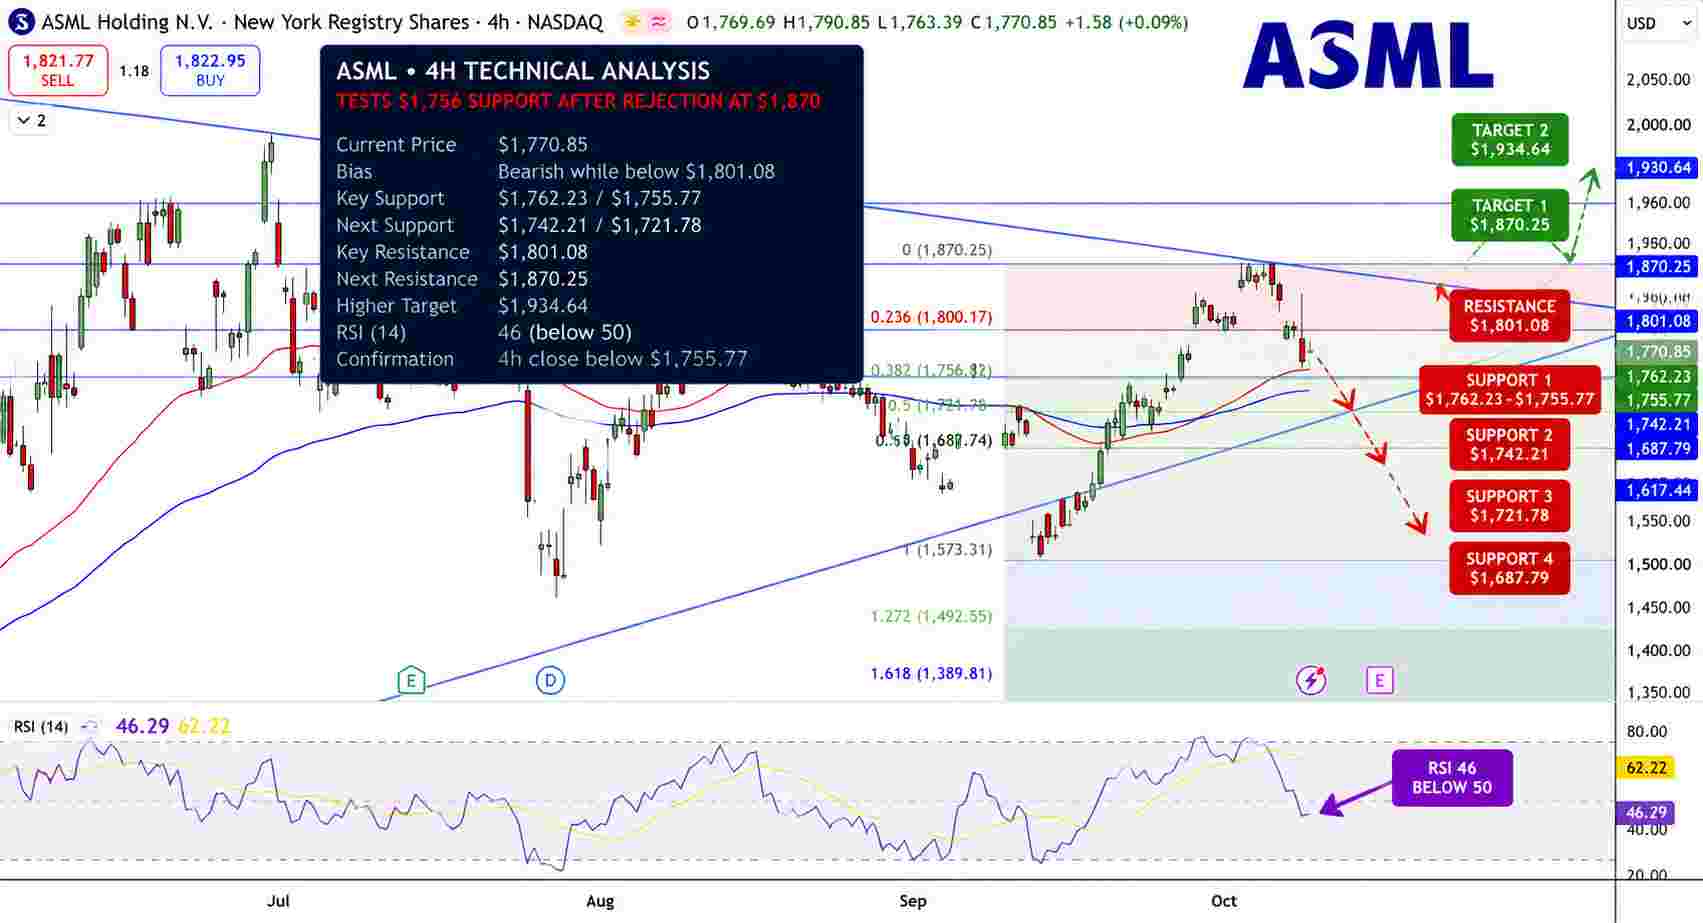
ASML Stock Price Chart - Source: Tradingview
The RSI is at 46, under the signal line at 62 and the neutral level at 50. The 50 SMA provides minor support around $1,762.23, along with the 38.2% retracement level near $1,756.82.
A sustained 4-hour close below the $1,755.77 support level would confirm a breakdown and open the door to $1,742.21 and $1,721.78. A sustained 4-hour close above $1,801.08 would improve the bullish recovery outlook and open the way to the $1,870.25 level and $1,934.64 above that.
For now, my bearish bias remains for ASML below $1,801.08.
Key Levels
Latest completed close: $1,769.79
Major Support: $1,755.77, $1,742.21, $1,721.78
Major Resistance: $1,801.08, $1,870.25, $1,934.64
RSI: Approximately 46
Recovery trigger: 4-hour close above $1,801.08
Breakdown trigger: 4-hour close below $1,755.77
Why is ASML stock in focus this Sunday?
ASML is in focus because the expectation is that Wednesday’s Q3 earnings report will be a strong one with guidance for 2026 already raised, High-NA is in production, and there is rising investment in artificial intelligence (AI) for semiconductor fabs.
What level confirms a stronger ASML recovery?
A 4-hour close above $1,801.08 improves the overall technical structure, favoring a test of the $1,870.25 level and $1,934.64 level above that. A 4-hour close below the $1,755.77 support level confirms a bearish shift and opens the way to the $1,742.21 and $1,721.78 levels.
Bottom Line
ASML has an advantaged structural position in the AI supply chain and is set to report earnings on Wednesday. For the time being, the main demand driver is the EUV capacity expansion. ASML maintains leadership with High-NA and Hyper-NA technology.
The main threats to the upside are valuation, customer execution and risk of China. Technically, the stock remains vulnerable to downside if it trades below $1,801.08. Fundamentally, the question is whether Q3 orders justify another upgrade to 2027 expectations. We believe the orders will come in and expect demand to remain strong.
Find out more