大摩:希慎兴业目标价下调至19港元 维持“与大市同步”评级

新浪港股
Aug 23
热点栏目 自选股 数据中心 行情中心 资金流向 模拟交易
客户端

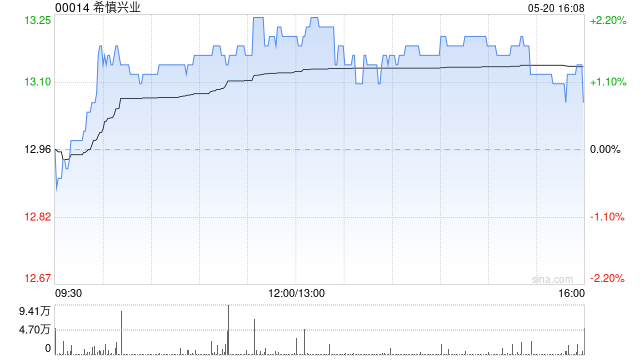
  摩根士丹利发布研报称,将希慎兴业(00014) 2026年的基础每股盈测上调6%,但将2027至2028年的预测分别下调2%及9%,以反映零售及写字楼表现优于预期、2027至2028财年资本化利息减少导致利息支出上升,以及最新租务及出租率预期。大摩将目标价由21港元下调至19港元,维持“与大市同步”评级。

  大摩预期公司股息将在2026至2028年间维持1.08港元。该行表示,希慎的净负债比率相较同行仍然偏高,加上在利园八期资本开支及永续债分派后,短期内现金盈利不足以覆盖股息分派。另外,该行认为利园八期或需更长时间才可带来明显租金贡献。

Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.
Most Discussed

  1. 1


  2. 2


  3. 3


  4. 4


  5. 5


  6. 6


  7. 7


  8. 8


  9. 9


  10. 10