热点栏目
客户端
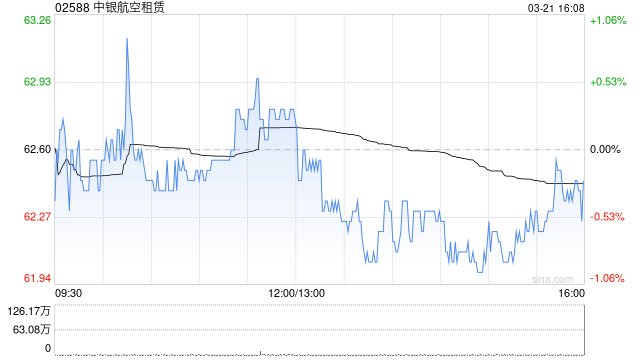
摩根士丹利发布研报称,调整中银航空租赁(02588)2026至2028年纯利预测,分别下调0.3%、1.9%及2.3%,以反映上半年业绩后的最新情况。该行认为美国十年期国债孳息率上升,投资者对回报率要求提高,因此将看好及基本情景下的目标市账率倍数分别由1.2倍及1.1倍,下调至1.1倍及1.0倍。目标价相应由92.3港元下调5.5%至87.2港元,维持“增持”评级。
摩根士丹利发布研报称,调整中银航空租赁(02588)2026至2028年纯利预测,分别下调0.3%、1.9%及2.3%,以反映上半年业绩后的最新情况。该行认为美国十年期国债孳息率上升,投资者对回报率要求提高,因此将看好及基本情景下的目标市账率倍数分别由1.2倍及1.1倍,下调至1.1倍及1.0倍。目标价相应由92.3港元下调5.5%至87.2港元,维持“增持”评级。
Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.