高盛:布鲁可给予“中性”评级 目标价72.40港元

新浪港股
Yesterday
热点栏目 自选股 数据中心 行情中心 资金流向 模拟交易
客户端

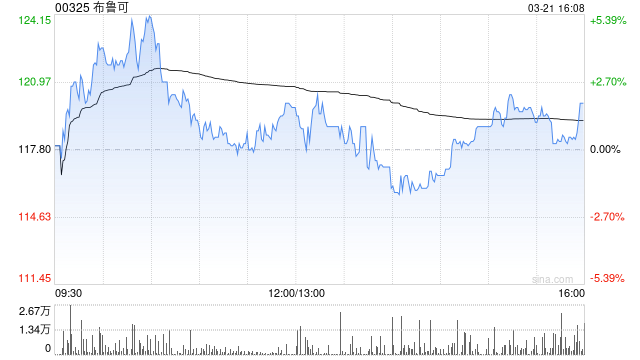
  高盛发布研报称,其覆盖的中国IP零售商及玩具公司2026年上半年及第二季度业绩好坏参半,名创优品(09896)盈利偏软,布鲁可(00325)销售则强于预期。给予布鲁可“中性”评级,目标价72.4港元;给予名创优品H股“买入”评级,目标价29.3港元。该行预计下半年中国IP/玩具需求维持韧性,但增长将因更高基数而放缓,海外趋势更趋分化。

  该行指出,名创优品内地销售强于预期,但海外分销商销售偏弱及经营去杠杆拖累利润率。布鲁可收入高于该行预期6%,受组装车模玩具及海外销售带动,但毛利率受到模具折旧、新产品爬坡及9.9元人民币价值带占比上升等因素拖累。

  高盛预计,下半年中国IP/玩具需求维持韧性,但增长将因更高基数而放缓。海外趋势更趋分化,布鲁可因渗透率低而增长能见度较强;名创优品则优先关注库存健康、门店生产力及盈利能力,而非快速扩张。毛利率仍是关键争论点,物流、采购及产品/地区组合或制约毛利率,布鲁可或有较佳规模效应,但海外供应链投资仍是抵销因素。

Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.
Most Discussed

  1. 1


  2. 2


  3. 3


  4. 4


  5. 5


  6. 6


  7. 7


  8. 8


  9. 9


  10. 10