大和:引述中国生物制药管理层重申今年收入增长双位数指引 给予“买入”评级

新浪港股
Sep 20
热点栏目 自选股 数据中心 行情中心 资金流向 模拟交易
客户端

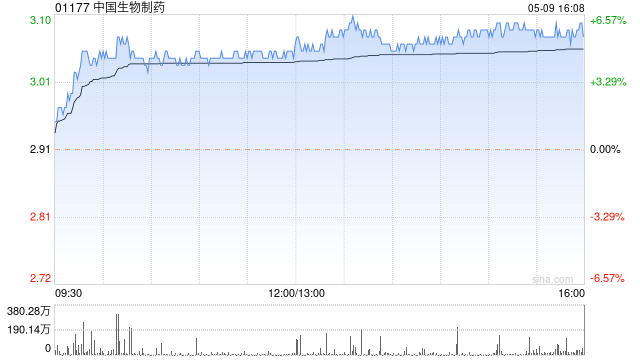
  大和发布研报称,日前举行医疗健康行业交流活动,中国生物制药(01177)管理层重申今年收入录得双位数同比增幅的指引未变,预期可由授权收入及创新药销售增长共同带动,并预期创新药销售加上授权收入将贡献全年收入一半。大和目前对中生制药评级为“买入”。

  该行指出,中生制药今年全年授权收入预期录3.55亿美元,除赛诺菲对外授权已确认1.35亿美元首付款外,预料下半年再确认阿斯利康就TQC3721(PDE3/4)的2亿美元首付款,以及Cipla就TQB2102的2,000万美元首付款,合计2.2亿美元。

  管理层亦透露,新获批创新药将是销售持续放量的主要动力,另预期仿制药业务将于今年见底后,在较低基数下明年或重拾增长。

Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.
Most Discussed

  1. 1


  2. 2


  3. 3


  4. 4


  5. 5


  6. 6


  7. 7


  8. 8


  9. 9


  10. 10