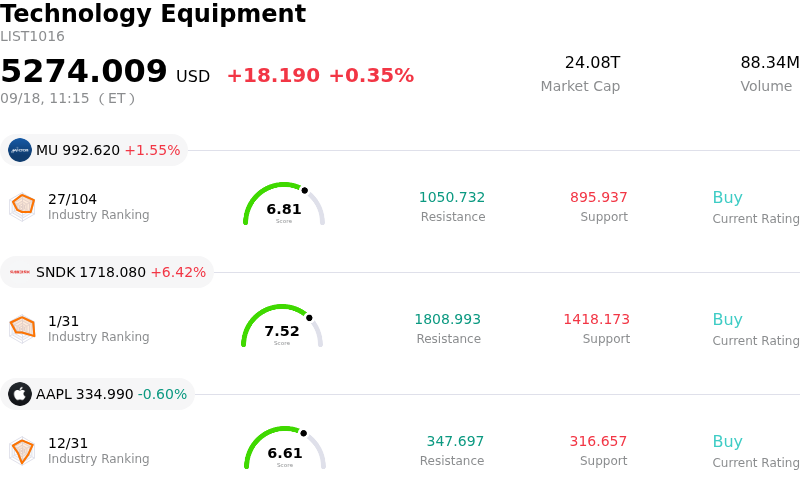
Qualcomm Inc (QCOM) moved down by 4.88%. The Technology Equipment sector is up by 0.35%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 1.54%; SanDisk Corporation (SNDK) up 6.46%; Apple Inc (AAPL) down 0.63%.
What is driving Qualcomm Inc (QCOM)’s stock price down today?
Qualcomm experienced notable downward pressure as short-term profit-taking took hold following a multi-week rally. Investors digested recent momentum driven by the company's high-profile, multi-generational AI data center silicon and optical connectivity partnership with Amazon Web Services. While the deal bolstered long-term optimism around Qualcomm's diversification beyond smartphones into hyperscale infrastructure, the rapid price appreciation prompted institutional profit-taking and technical resistance, pulling shares lower across the session.
Adding to the selling momentum was heightened caution from Wall Street analysts and research downgrades highlighting potential near-term fundamental constraints. Analysts pointed to margin compression across the semiconductor business unit driven by persistent supply chain cost inflation, including higher expenses for wafer fabrication, advanced packaging, and testing. Additionally, soft consumer handset demand and a shift by major smartphone original equipment manufacturers toward prior-generation chipsets continue to limit pricing power, making it challenging for Qualcomm to immediately pass cost increases on to customers under fixed-price contracts.
Investors are also weighing structural risk factors in Qualcomm's core mobile franchise. Market participants remain focused on Apple's ongoing transition toward proprietary modem hardware, which is expected to gradually reduce high-margin revenue streams over coming launch cycles. Concurrently, aggressive competitive releases in next-generation smartphone processors from rivals are intensifying mobile market competition. Although Qualcomm's expansion into automotive, internet of things, and custom AI silicon offers substantial long-term optionality, the market appears focused on the near-term cash-flow transition and margin pressures, leading to a risk-off stance among market participants.
Technical Analysis of Qualcomm Inc (QCOM)
Technically, Qualcomm Inc (QCOM) shows a MACD (12,26,9) value of 3.429, indicating a buy signal. The RSI at 56.390 suggests neutral condition and the Williams %R at 40.356 suggests buy condition. Please monitor closely.
Media Coverage of Qualcomm Inc (QCOM)
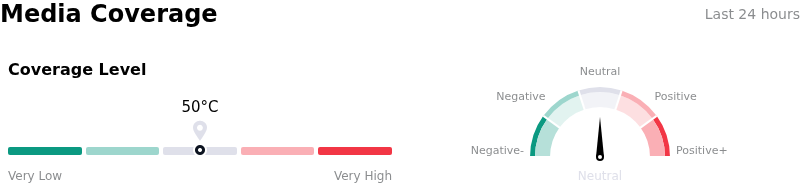
In terms of media coverage, Qualcomm Inc (QCOM) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Qualcomm Inc (QCOM)
Qualcomm Inc (QCOM) is in the Technology Equipment industry. Its latest annual revenue is $44.28B, ranking 6 in the industry. The net profit is $5.54B, ranking 9 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $194.11, a high of $400.00, and a low of $100.00.
More details about Qualcomm Inc (QCOM)
Company Specific Risks:
- Accelerating Loss of Apple Modem Share: Management confirmed that Qualcomm's socket share in upcoming iPhone models will fall materially below prior estimates of 20%, expecting Apple-related product revenue to drop roughly 50% sequentially into the December quarter as Apple accelerates its transition to in-house modems.
- Handset Demand Drag and Cost Inflation: Core smartphone chip revenue plunged 20% year-over-year as mobile original equipment manufacturers cut chipset purchases, while broad-based input cost inflation in wafer fabrication, testing, and memory continues to compress QCT gross margins faster than planned price increases can offset.
- Margin Dilution from Custom AI Contracts: Analysts caution that initial data-center revenue from Qualcomm's custom AI silicon agreement with Amazon carries lower gross margins—imposing an estimated 1.5% to 2.0% drag on QCT weighted average gross margins—while substantial revenue realization depends on multi-year purchase orders rather than immediate cash flows.
- Negative Earnings Revisions and Overvaluation Concerns: Wall Street research firms, including Zacks with a Strong Sell rating, have revised near-term earnings per share projections downward, warning that the stock's elevated forward earnings multiple leaves little margin for error given that non-handset growth will not fully offset smartphone weakness until FY2028.
Find out more