交银国际:华泰证券目标价上调至22港元 维持“买入”评级

新浪港股
Yesterday
热点栏目 自选股 数据中心 行情中心 资金流向 模拟交易
客户端

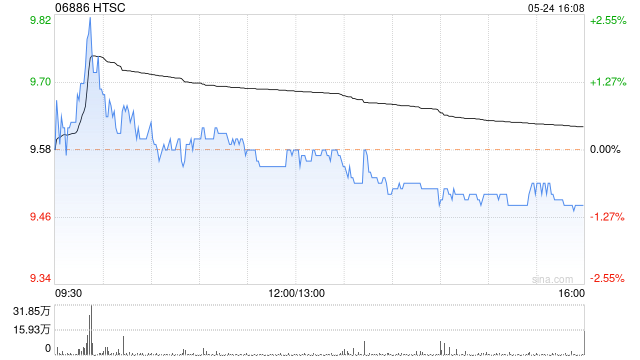
  交银国际发布研报称,上调华泰证券(06886)目标价至22港元,维持“买入”评级。

  该行更新2026-2028年预测,预计未来三年公司盈利能力持续增强,归母净利分别达212/233/250亿元人民币。2026年以来公司股价表现与业绩表现仍有一定落差,考虑到其在深耕跨境财富管理、服务中资企业出海、布局AI降本增效等面向具有较大潜力,公司现价对应2026年约0.63倍P/B,估值仍有进一步修复空间。

  公司2026年第二季以来业绩增速进一步骤加快,上半年总资产较2025年末增加25.5%,归母净利同比增54.9%,业务发展呈现明显扩张态势,自营投资、经纪、投行等多业务线同步改善。

Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.
Most Discussed

  1. 1


  2. 2


  3. 3


  4. 4


  5. 5


  6. 6


  7. 7


  8. 8


  9. 9


  10. 10