热点栏目
客户端
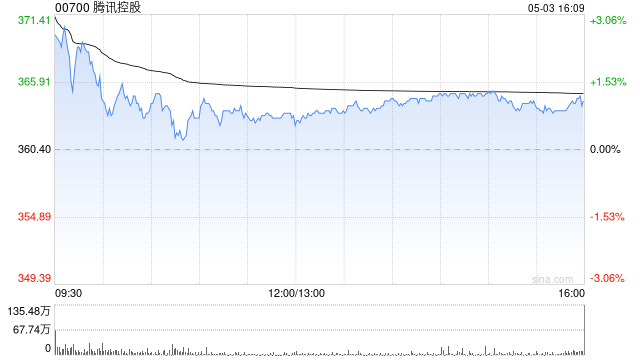
花旗发布研报称,重申腾讯控股(00700)“买入”评级,目标价765港元。该行认为,微信“小微”独特定位有望成为中国终极消费AI代理。腾讯并非推出独立应用,而是将“小微”原生嵌入微信,直接利用其庞大月活跃用户基数、专有社交图谱,以及已建立并验证的小程序电商轨道。
该行指出,相对于Meta组建第三方连接器,以及阿里巴巴-W(09988)等国内同业或面对中国“围墙花园”下较大的API阻力,微信相对中立的平台定位及已建立的垂直合作伙伴关系,预计可提供无可比拟的分发及交易护城河。与Meta的Muse类似,该行相信,随着中国代理式商务起飞,“小微”可通过交易抽成及广告,解锁可观的长期变现机会。
该行称,腾讯自6月起已与选定商业伙伴测试“小微”代理功能,长期有望接入更广泛生态伙伴,在微信内自主执行更复杂的用户流程及交易动作。
Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.