花旗:敏华控股维持“买入”评级 目标价削至3.6港元

新浪港股
Oct 15
热点栏目 自选股 数据中心 行情中心 资金流向 模拟交易
客户端
10月20-22日上海黄浦江畔,2026可持续全球领导者大会再度来袭。诺奖、图灵奖得主现场讲述科技未来与趋势,更有“解救”焦虑、内卷时代的网红教授——麦克法兰与项飙现场对话! 名额有限,手慢无。让我们共赴可持续之约!【点击报名】

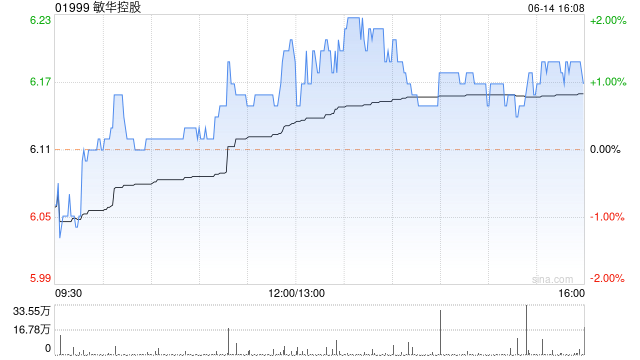
  花旗发布研报称,敏华控股(01999)早前发盈警,截至2026年9月底止半年度纯利料同比减少70%至90%,该行仍维持“买入”评级,目标价由5.6港元削至3.6港元,但指敏华控股仍是花旗中国家居板块中唯一获“买入”评级的公司,对同业欧派家居及索菲亚家居,则维持“沽出”评级。

  花旗指出,集团上半财年利润下滑主要受化工原材料价格上涨,及2025年12月收购的美国业务Southern Motion产生一次性减值影响。花旗预计,由于下半财年将不再录得相关减值,加上新产品推出后带动平均售价提升,下半财年净利润有望较上半财年回升约1.8倍至6.64亿港元,全年纯利料为8.94亿港元,2027年升至17.96亿港元。

  花旗认为,敏华控股在中国及美国功能沙发市场占据主导地位,受惠于中美市场稳定的替换需求及功能沙发渗透率持续提升,该行相信敏华控股有望在美国业务完成重组后逐步改善盈利表现。

Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.
Most Discussed

  1. 1


  2. 2


  3. 3


  4. 4


  5. 5


  6. 6


  7. 7


  8. 8


  9. 9


  10. 10